Property Investment
Can I afford an investment property?
In this article, you’ll learn how much money you need for these 3 factors. That way, you’ll know how much you need to start investing in property.
Property Investment
3 min read

Author: Andrew Nicol
Founder, 20+ Years' Experience Investing In Property, Author & Host
Yesterday the Reserve Bank kept the Official Cash Rate (OCR) at 2.75%.
That caught almost everyone off guard. Financial markets were about 95% sure we'd get a hike, taking the OCR to 3%.
But all 5 big banks got the call wrong.
So if you've got a mortgage, that's good news … for now.
Because the Reserve Bank also made it pretty clear … it isn't finished putting rates up yet. The question is when the next hike comes.
My view? We’ll probably get the next increase on the 8th December. And most forecasters now expect at least one more hike by early next year.
But why did the Reserve Bank shock everyone and hit pause? And what does it mean for your mortgage?
I’ve been going through all the Reserve Bank’s docs. Here’s what I found.
There were three main reasons the Reserve Bank decided to hold off.
Inflation is sitting at 3.7%. That's down from 4.1% in the June quarter.
It's still above the Reserve Bank's target of 1% to 3%. But the latest number came in 0.2% lower than what the Reserve Bank had expected.
That's not a huge amount under expectations. But inflation is moving in the right direction. So it gives the Reserve Bank a little breathing room to wait and see.
The Reserve Bank's big worry was that higher petrol prices would push up the price of everything else.
After all, it takes diesel to power the trucks to get your food to the supermarket. So businesses will often put up their prices to cover those extra costs. And suddenly your groceries cost more.
So far, businesses haven't passed on as much of that extra cost as the Reserve Bank originally feared.
Part of that is because of the next point.
Our economy is growing again, but it's still fragile. And Kiwis have stopped spending as much.
Aggregate savings are sitting at 3.7%, compared with a 10-year average of around 1%.
Businesses that sell their stuff offshore (like farmers) are doing well. But businesses that sell to Kiwis (like restaurants and butchers) are doing it tougher.
Kiwis aren’t opening their wallets much. So, businesses can’t really put up prices.
In the short term, it's a little bit of relief.
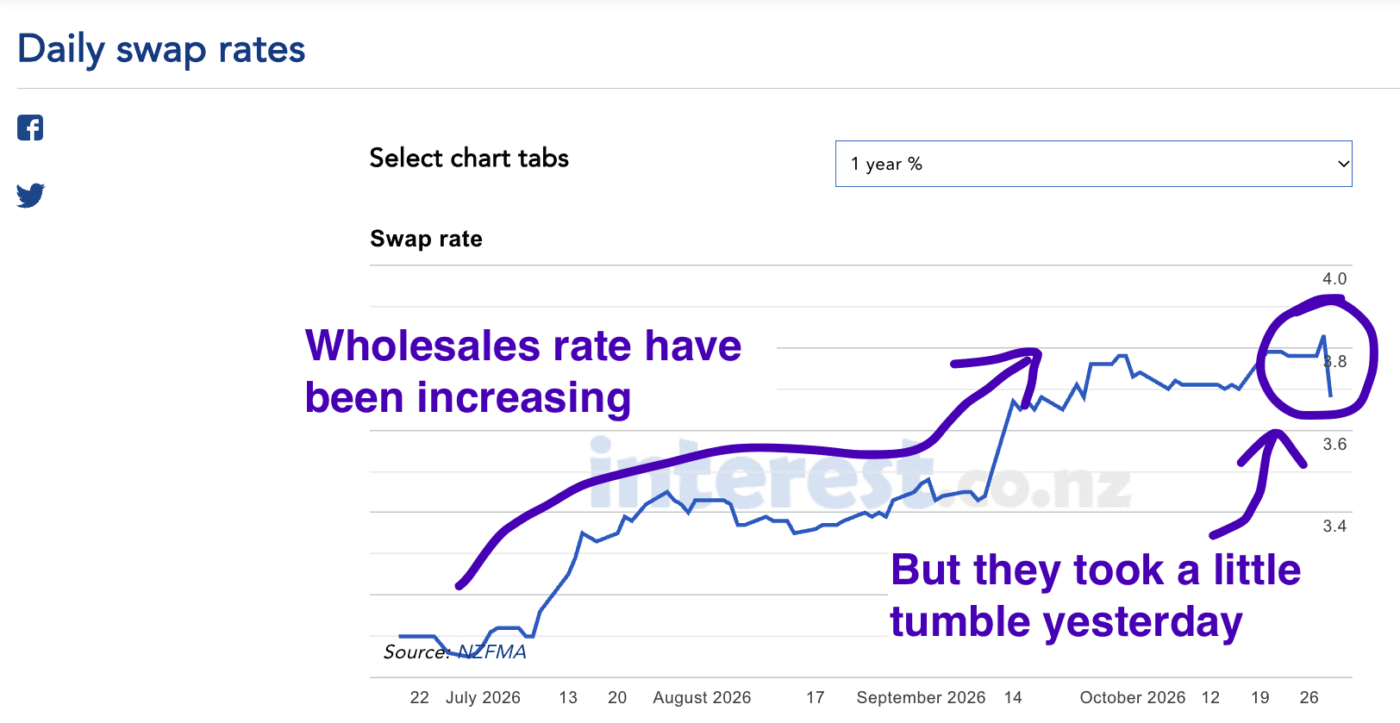
Banks set fixed mortgage rates based on where they think interest rates are heading. Before yesterday, the wholesale interest rate markets were pricing in a lot of hikes. Now they're not pricing in as many.
That pulled down wholesale interest rates. Think of these as what it costs banks to borrow money and lend it to you and me for our mortgages.
And that means the banks aren’t under as much pressure to jack up your mortgage rate.
But don't expect the banks to rush out and cut their rates.
It’s more likely that they leave their interest rates where they are. And they do a bit more discounting in the background when you go and fix your mortgage.
That’s because the Reserve Bank could well increase rates again in December anyway.
So if your mortgage is coming up for renewal in the next few weeks, I wouldn't make a big decision based on yesterday alone.
After all, the Reserve Bank also expects inflation to bounce back up to 4.4% in the December quarter.
That's why I'd treat yesterday as a delay. I wouldn't treat it as the end of interest rate hikes.
Founder, 20+ Years' Experience Investing In Property, Author & Host
Andrew Nicol, Managing Director at Opes Partners, is a seasoned financial adviser and property investment expert with 20+ years of experience. With 40 investment properties, he hosts the Property Academy Podcast, co-authored 'Wealth Plan' with Ed Mcknight, and has helped 1,894 Kiwis achieve financial security through property investment.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser